The Death of the Batch Process
The international financial system is breaking apart. Legacy clearing systems are unable to keep pace with the swiftness of today’s business. Batch processing protocols were invented in a slower time. Latency is their obstacle. They bleed capital in the form of high transaction fees and are strangled by data silos. With the number of low-dollar transactions hitting distributed networks now, settlement and authentication need to be done in real time to handle this. We are seeing a complete paradigm change from the use of old plumbing to a growing need for high-frequency processing.
Consider the current two ecosystems that are pushing the absolute scale limits of this required scale. Sovereign central banks are creating digital fiat for billions of people and the ruthless global iGaming industry. They seem entirely disconnected. One who is obsessed with the macro-economic dominance and the sovereignty of fiat. The other one was just completely preoccupied with user friction and regulatory viability. However, they are in the same existential crisis. Their job is to transfer very small amounts of value across borders in real time, securely, and without any issues. The architecture that is needed changes everything.
Weaponizing the Digital Deposit
The digital yuan (e-CNY) was initially conceived as a pilot initiative to convert physical currency into digital form. That era is over. Now the underlying architecture is a mix of account-based and token-based functions to enable completely offline transactions. Near field communication keeps the system completely resilient in the event of a complete failure of telecommunications. By the end of 2025, the People’s Bank of China had overseen 3.48 billion transactions. That’s 16.7 trillion yuan going down the rails, state-owned. The turning point came as the PBOC started offering interest rates for commercial banks on e-CNY wallets. They created a simple token into a pretty highly weaponized digital deposit currency.
This was a surgical sweep. It rendered private stablecoins that can generate yield in the crypto space useless with a dollar backing. It directly targeted the giant corporations at home, such as Alipay and WeChat Pay, which have lots of floating capital. The state mandated these non-bank platforms to go through the NetsUnion Clearing Corporation (NUCC). It’s a direct-connection model that’s been blown to bits in one night. Centralized clearing, which took away the vast capital float exploitation that lined the margins of tech monopolies, restored total oversight. With distributed, cloud-native micro-services, the NUCC defies impossible concurrency and outstrips traditional inter-bank systems in the middle of commerce. They created a system in which an abnormal amount of traffic in one area does not slow traffic in another area. Failure is not an option
The Commercial Crucible
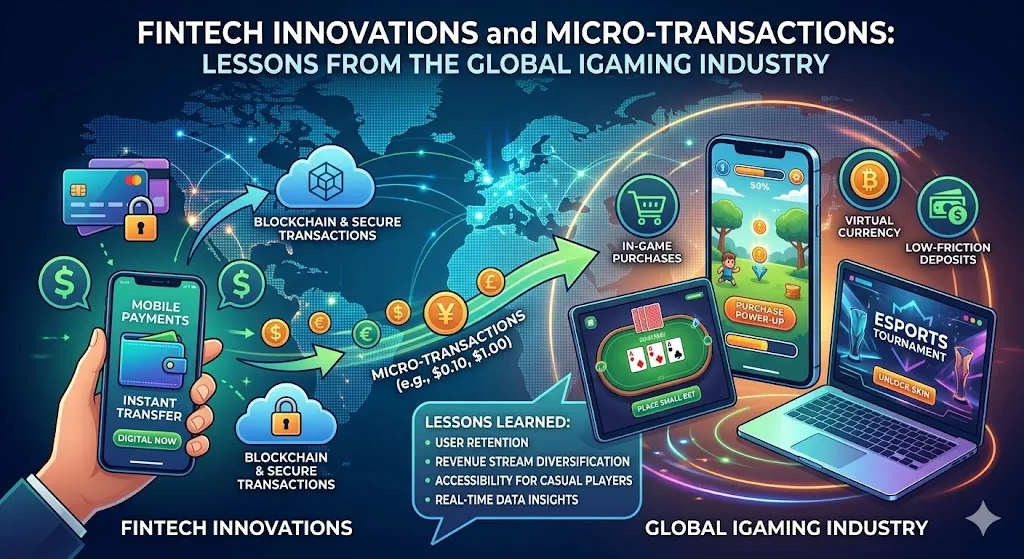
As central banks develop enormous national rails to track systemic risk, the hottest laboratory for those very same technologies is in the commercial arena. For the iGaming/online sports betting businesses, revenue margins are extremely thin, and they are running on a huge volume. When it comes to complex micro-bets and fast account deposits, high-volume interactive gaming platforms have to process them nearly friction-free. It’s the technical demands here that are vicious. Players want instant deposit and payout options. Friction kills conversion. The usability of the onboarding sequence is crucial to the retention of users. DraftKings and other operators around the globe are engaged in an arms race to cut latency and deal with a compliance minefield.
They’ve got to perform Know Your Customer (KYC), Anti-Money Laundering (AML), and identify geolocation protocols in mere milliseconds. If a user expects to be able to cash in their winnings during the weekend before they complete a beer, a standard T+2 settlement cycle isn’t really sufficient. The traditional credit card networks did this industry a major disservice many years ago, as they limited access to the gaming industry by restricting the merchant category codes (MCC) assigned to merchants by their issuing banks. High decline rates. Exorbitant processing fees. A huge risk of being ripped off. The industry needed a whole new method to transfer funds.
Bypassing the Legacy Cartels
Payment orchestration provided the escape route. Nuvei, Trustly, and Genome bundled up hundreds of payment methods in one, no-pain APIs. They move capital from place to place as conditions in a region can change, and if a region is cheaper to do business in, they locate there instead. The weapon of choice was open banking. An ‘account-to-account (A2A) transfer’ is a transaction that skips all the intermediaries. Trustly has turned the onboarding process into a powerful weapon in their “Pay N Play” model. It pulls verified identity information such as name, IBAN, and sanctions list status—right from the user’s bank—on the spot.
The financial transfer and the regulatory verification take place at the same time. Conversion rates skyrocket. Time to onboard reduces to seconds. The technical logistics required to maintain this are rigid. Watch the VIP Preferred SDK that has been used extensively in North America. Data payload constraints are mathematically precise. The Date Of Birth must be a 10-character string. The cycle is a closed loop. When you deposit funds into a verified PayPal account, you can only withdraw from that same account. No disruption to the financial circuit. Money launderers hit a brick wall.
Identity as the Transaction Payload
Carrying the cash is just one of the challenges. You must establish who is moving it and where they’re standing. The old way of using the internet to be anonymous is gone. Fraud rings use advanced VPNs and account takeover to take advantage of these high-frequency networks. IP addresses are utterly unusable for verified locations. Gaming operators use military-level cybersecurity, such as geo-comply to bust through the digital veil. They don’t check network data. They inspect the equipment.
They triangulate GPS positions, local wireless MAC addresses, and cell tower signals. This sets a device identity that can never be changed. This intelligence eradicates the threat of chargeback. If a consumer maliciously challenges a bet, geolocating data from the past will be used to show that the user was present in the device’s location when the bet was taken. The burden of proof shifts instantly. Machine learning algorithms evaluate risk as it happens and only hard authenticate when anomalies are noticed and are on the upswing.
Zero Latency, Zero Anonymity
These two extreme environments are rapidly shaping the destiny of modern money. Central bank infrastructure and sports betting platforms are moving towards a common, standard design. Rent-seeking middlemen are being eliminated from the transaction lifecycle. Settlement times are accelerating to absolute zero. All digital value transfers are now permanently linked with biometric identity and geographic location data. The digital transaction packet is the exact physical reality of the user. The system bottlenecks are no longer due to speed or sheer scale. Absolute, undeniable security is the ultimate mandate and an integral part of the digital deposit.
Post Author
